

25d Risk Reversal ETH and Deribit 25 Delta Risk Reversal Definition: Crypto and Equity Options Skew Guide
Executive SynthesisMaster the 25d risk reversal ETH metric and Deribit 25 delta risk reversal definition to decode institutional crypto options skew crash hedging and cross asset equity flows on Saku.
What Is the Deribit 25 Delta Risk Reversal Definition and 25d Risk Reversal ETH
If you want to know whether institutional market makers crypto hedge funds and quantitative volatility desks are positioning for an explosive upside rally or bracing for a violent liquidation cascade you cannot rely on spot price candles alone. Institutional desks telegraph their true directional conviction inside the options implied volatility surface specifically through the 25 delta risk reversal.
Under the standard Deribit 25 delta risk reversal definition the metric measures the exact implied volatility spread between an out of the money 25 delta call option and an out of the money 25 delta put option sharing the exact same expiration date. When quantitative traders monitor 25d risk reversal ETH or Bitcoin options skew they calculate 25 Delta Call Implied Volatility minus 25 Delta Put Implied Volatility.
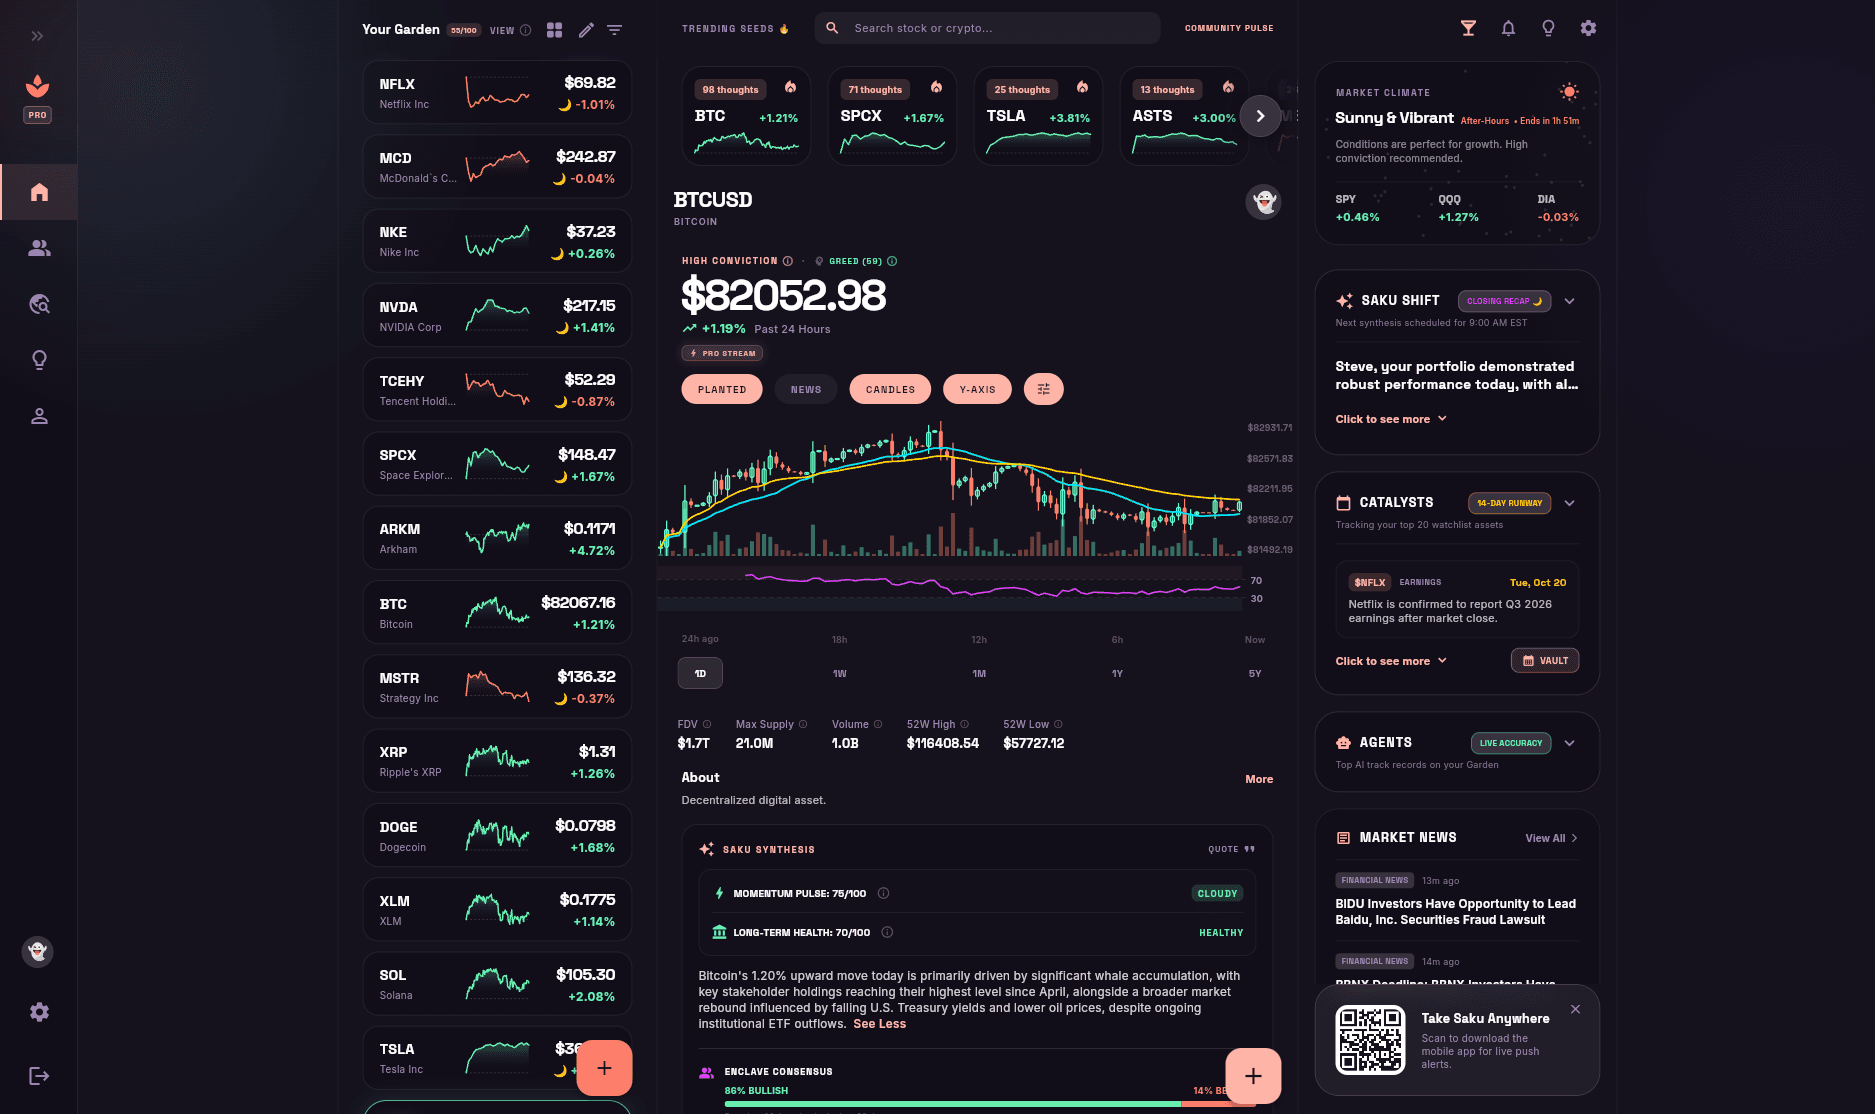
Having spent eighteen years inside enterprise banking at TD Bank Group architecting financial market technology and holding both FINRA and IIROC regulatory licenses I watched institutional derivatives desks use 25 delta risk reversals as their primary real time fear and greed barometer. We built Saku Financial Inc. to translate these complex institutional options skew and dark pool signals into plain English inside a 100 percent free ad free terminal across Web iOS and Android.
See Live Dark Pool Flow & AI SEC Synthesis in Action
Don't just read about institutional order flow—track it live on your favorite stock or crypto ticker right now.
How to Read Positive vs Negative ETH 25d Risk Reversal Readings
Why do institutional options desks focus specifically on the 25 delta strike across Ethereum and Bitcoin options chains. Because 25 delta options sit at the exact liquid sweet spot on the volatility smile where institutional portfolio managers execute directional call sweeps and protective tail risk put hedges without overpaying for deep in the money intrinsic value.
When the eth 25d risk reversal is positive meaning 25 delta call implied volatility is trading at a premium to 25 delta put implied volatility institutional whales are aggressively bidding up out of the money calls to capture upside convexity. Conversely when the 25d risk reversal ETH flips deeply negative to minus five percent or minus ten percent institutional desks are paying a massive volatility premium for downside put protection ahead of a macro shock or liquidation cascade.
As we demonstrated in our foundational masterclasses on the 25 delta risk reversal definition and options skew trading guide and what is put skew and institutional crash hedging extreme negative skew readings also serve as powerful contrarian bottom signals once forced selling exhausts itself.
Why Crypto Options Skew Differs From S and P 500 Equity Volatility Smiles
One of the most important structural lessons for cross asset traders is understanding why digital asset options skew behaves differently than traditional US equity index options. In the S and P 500 and Nasdaq 100 options markets the 25 delta risk reversal is almost permanently negative because pension funds and long only endowments continuously buy protective puts and sell covered calls.
In twenty four seven cryptocurrency derivatives markets like Ethereum and Bitcoin however the volatility surface is bimodal. During institutional bull expansions spot ETF inflows and sovereign treasury accumulation cause 25d risk reversal ETH and BTC skew to flip sharply positive as traders chase upside call gamma. During regulatory scares or macroeconomic tightening crypto skew violently inverts into deep put skew within hours.
Inside Saku you can monitor this cross asset transmission directly by comparing our live Ethereum ETHUSD AI price target and support levels dossier and Bitcoin BTCUSD AI price target and dark pool hub alongside high beta crypto equities like MSTR AI price target and quant analysis and COIN AI price target and institutional flow.
Track live dark pool flow & hatch your Personal AI Quant at Desk #4.
Combining 25d Risk Reversals with Dealer Gamma Call Walls and Put Walls
While the 25 delta risk reversal tells you the directional tilt of institutional implied volatility pricing you still need to know the exact dollar strike prices where market makers will be forced to buy or sell the underlying asset. That requires mapping mechanical options Call Walls and Put Walls alongside the zero gamma flip level.
When eth 25d risk reversal surges into positive territory while spot price approaches a major overhead Call Wall dealers who sold those 25 delta calls are forced to buy spot ETH or perpetual futures to delta hedge their exposure fueling a mechanical gamma squeeze. Conversely when 25d risk reversal ETH plunges deeply negative and spot breaks below a major Put Wall dealers enter negative gamma territory and must sell into the drop.
By combining options skew with the framework in our guide to trading call walls put walls and the zero gamma flip level self directed traders stop guessing where pullbacks will stabilize and start aligning entries with mechanical dealer hedging floors.
How Weekend ETH and BTC 25d Skew Telegraphs Monday Equity Market Opens
Why should traditional stock and ETF traders care about Deribit 25 delta risk reversal metrics on a Saturday or Sunday. Because when Wall Street equity exchanges close at 4:00 PM EST on Friday twenty four seven cryptocurrency options and spot markets remain the only liquid institutional barometer pricing global geopolitical and macroeconomic risk in real time.
When a weekend geopolitical shock or unexpected liquidity announcement occurs institutional macro desks immediately reprice 7 day and 30 day eth 25d risk reversal and Bitcoin put skew hours before S and P 500 futures open on Sunday evening. A sudden weekend collapse in crypto 25d risk reversals reliably warns equity traders of a risk off Monday morning gap down across semiconductor and AI stocks.
To help you prepare for these cross asset catalysts without staring at derivative tables all weekend Saku provides a live Enclave Catalyst Calendar tracking upcoming FOMC decisions CPI inflation releases corporate earnings and token supply unlocks alongside our automated Weekend Outlook briefings.
Automating 24/7 Skew and Support Surveillance with Saku AI Quant Agents
Manually calculating 25 delta call minus 25 delta put implied volatility spreads across multiple expirations while tracking off exchange dark pool prints is impossible for an individual investor working a full time job. Inside the Saku Living Agent Sanctuary our autonomous AI architecture automates that entire institutional workflow.
Every day at 10:00 AM EST seven days a week our autonomous Crypto Momentum House Quant Agent scans twenty four seven digital asset momentum volatility regimes and structural support channels to lock a verified 1 month prediction on our public Oracle Ledger. Even better as we detailed in our guide to the best AI agents to monitor the stock market and crypto 24/7 you can claim Workstation Number Four for free to hatch your own Personal AI Quant Companion.
Your Personal Companion guards your chosen crypto or equity ticker around the clock and delivers automated institutional shift dossiers at 9:00 AM EST 12:00 PM EST and 4:30 PM EST. Launch the 100 percent free ad free Saku terminal on Web iOS or Android today to trade with institutional options and dark pool clarity.
What is the Deribit 25 delta risk reversal definition?
Under the Deribit 25 delta risk reversal definition the metric equals the implied volatility of a 25 delta out of the money call option minus the implied volatility of a 25 delta out of the money put option for the same expiration date measuring whether institutional traders are paying more for upside call exposure or downside put protection.
What does a negative 25d risk reversal ETH reading mean?
A negative 25d risk reversal ETH reading means 25 delta ETH put options are trading at a higher implied volatility than 25 delta ETH call options indicating that institutional traders and market makers are actively bidding up downside crash protection.
How does Saku help retail traders track crypto and equity options walls?
Saku translates complex options Call Walls Put Walls support and resistance channels and off exchange dark pool flows into plain English inside a 100 percent free ad free terminal across Web iOS and Android complete with autonomous AI monitoring agents.
Related Institutional Research
View All Research →Which Solutions Combine Dark Pools with AI Document Analysis and AI Diligence: The 2026 Guide
Discover which solutions combine dark pools with AI document analysis and which dark pool platform offers AI diligence by uniting off exchange block prints with RAG AI SEC filing synthesis on Saku.
Recent News Catalysts and Upcoming Earnings Dates Calendar: How AI Tracks TSLA NVDA PLTR and SPCX Events
Track recent news catalysts and upcoming earnings dates for TSLA NVDA PLTR AAOI and SPCX using the Saku 14 day Enclave Catalyst Calendar dark pool flow and RAG AI filing synthesis.
Crypto Options and ETFs: Why You Need a Unified Macro Radar
Stop suffering from app fatigue. Discover how combining every asset class into a living breathing engine changes the landscape of traditional watchlists into a one stop shop for research and learning.
Best AI Agents to Monitor the Stock Market 24/7: How Autonomous Quant Companions Guard Your Watchlist
Looking for AI agents to monitor the stock market and crypto 24/7? Discover how Saku autonomous House Quant Agents and your free Personal AI Companion at Workstation 4 audit dark pools SEC filings and support walls nonstop.
Steven White, MBA
Formerly FINRA & IIROC LicensedFounder & Architect, Saku Financial Inc. • 18-Year TD Bank Group Veteran
Steven spent 18 years at TD Bank Group architecting enterprise product operations, strategy, and financial market technology, and previously held both FINRA and IIROC regulatory licenses. He built Saku to level the playing field—giving self-directed retail investors the same institutional-grade RAG AI synthesis, dark pool order flow, autonomous quant agents, and verified prediction ledgers used by the smart money.
Put Institutional Intelligence to Work.
Track live dark pool prints, read instant RAG AI SEC filing syntheses, and hatch your own personal AI quant companion inside the Saku Sanctuary.