

How Can Investors Stress Test a Portfolio for an Artificial Intelligence Market Correction
⚡ Executive SynthesisLearn how investors can stress test a portfolio for an artificial intelligence market correction using dark pool distribution prints 25 delta options skew and RAG AI SEC filing audits.
Why Asking How to Stress Test a Portfolio for an AI Market Correction Is Critical in 2026
Across family offices quantitative hedge funds and self directed trading desks one urgent risk management question is dominating the conversation how can investors stress test a portfolio for an artificial intelligence market correction. Over the past three years capital concentration inside megacap semiconductor hyperscale cloud data center power and enterprise software equities has reached levels that surpass the late 1990s telecommunications buildout.
Even investors who believe they hold a diversified portfolio of index exchange traded funds technology growth stocks and digital assets frequently discover during a volatility shock that eighty percent of their holdings are driven by a single macro factor hyperscaler artificial intelligence capital expenditure. When an entire portfolio relies on continuous GPU cluster orders and aggressive forward earnings multiples a sudden deceleration in AI capital spending or a sovereign semiconductor tariff can trigger simultaneous drawdowns across every position you own.
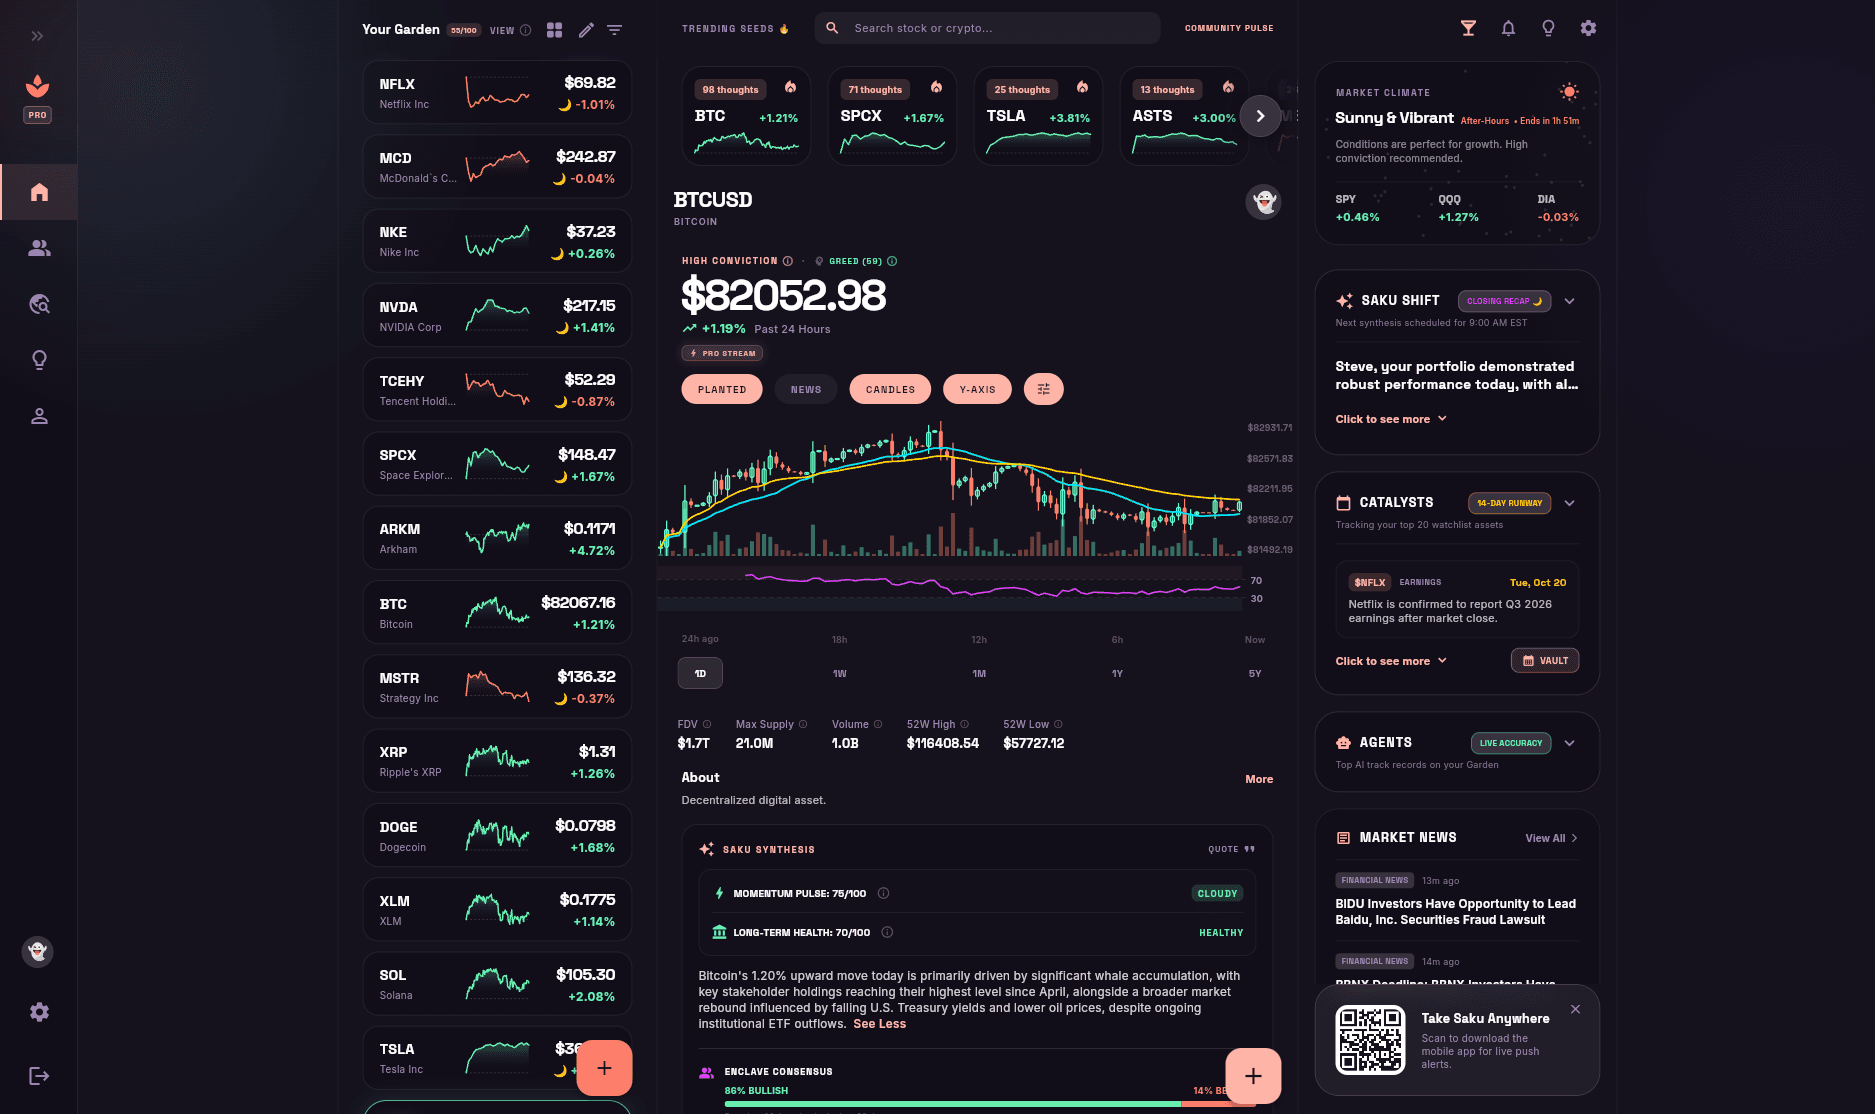
Having spent eighteen years inside enterprise banking at TD Bank Group architecting financial market technology and holding both FINRA and IIROC regulatory licenses I saw firsthand how institutional risk committees stress test concentrated portfolios before a correction hits. We engineered Saku Financial Inc. to give self directed retail traders the exact same dark pool topography options skew telemetry and automated SEC filing diligence required to stress test and protect their portfolios in real time.
See Live Dark Pool Flow & AI SEC Synthesis in Action
Don't just read about institutional order flow—track it live on your favorite stock or crypto ticker right now.
Step 1 Auditing Hidden AI Capex Correlation and Crowded Hedge Fund Positioning
The first step when learning how can investors stress test a portfolio for an artificial intelligence market correction is uncovering hidden factor correlation and multi manager pod crowding. Retail investors often assume that owning a semiconductor manufacturer an electric utility provider a liquid cooling hardware supplier and a cloud database company provides sector diversification. In reality institutional quantitative pods trade all four of those tickers inside the exact same momentum basket.
What happens when a single hyperscaler guides quarterly capital expenditure two billion dollars below consensus expectations. As we detailed in our institutional post mortem on the anatomy of a hedge fund blow up margin cascades and crowded trades leveraged multi manager pods are forced by automated Value at Risk limits to liquidate the entire AI infrastructure basket simultaneously.
Inside Saku you can stress test your portfolio exposure to this factor crowding by tracking our deterministic Momentum Pulse and Long Term Health scores alongside five day relative volume velocity. When multiple seemingly unrelated stocks in your watchlist exhibit identical five day price velocity and simultaneous off exchange volume spikes you are not holding a diversified portfolio you are holding a single leveraged bet on AI infrastructure momentum.
Step 2 Tracking Off Exchange Dark Pool Distribution Before Lit Charts Break
How do you know when sovereign wealth funds pension allocators and billion dollar prop desks are quietly reducing their artificial intelligence equity exposure before the public Nasdaq index rolls over. Institutional portfolio managers never dump five million shares of a crowded semiconductor stock onto the public lit order book at 10:00 AM EST because doing so would crash their own execution price.
Instead institutional distribution begins weeks earlier inside off exchange Alternative Trading Systems and private broker dealer dark pools while retail traders are still buying the dip on lit exchanges. As we explained in our deep dive on which dark pool secondary platform offers AI diligence tracking the divergence between stagnant lit exchange price action and heavy off exchange block selling is one of the highest signal stress tests in modern finance.
Furthermore institutional insiders at major technology companies telegraph valuation exhaustion through regulatory disclosures. By combining live dark pool block monitoring with our automated SEC Form 4 insider trading tracker Saku alerts you the moment C suite executives and board directors accelerate open market share sales into retail euphoria.
Track live dark pool flow & hatch your Personal AI Quant at Desk #4.
Step 3 Stress Testing Downside Air Pockets Using 25 Delta Risk Reversal and Put Walls
A true institutional stress test does not just ask whether a stock can fall it calculates the exact price levels where mechanical dealer selling will accelerate a correction into a crash. In modern equity markets options market makers control short term price stability through gamma hedging.
To stress test any AI stock in your portfolio before earnings or macro catalysts you must audit two specific options market structure metrics. First examine the 25 delta risk reversal options skew. When institutional portfolio managers become nervous about an impending AI market correction they aggressively bid up out of the money 25 delta protective puts while selling 25 delta calls to finance the hedge causing the risk reversal skew to plunge deeply negative days before the stock price drops.
Second identify the exact strike price of the stock mechanical floor and ceiling by understanding what is a call wall in options trading and what is a put wall in options trading. As long as an AI stock trades above its major Put Wall dealer hedging buffers volatility. The moment spot price breaks below the Put Wall the stock enters a negative gamma air pocket where options dealers are mathematically forced to sell underlying shares into a falling market.
Step 4 Running Automated SEC 10 K and 10 Q Balance Sheet Stress Tests with Saku RAG AI
During a bull market frenzy investors ignore accounting quality and focus exclusively on revenue growth narratives. During an artificial intelligence market correction stocks with fragile balance sheets circular vendor financing and aggressive accounts receivable recognition suffer seventy to eighty percent drawdowns while fortress cash flow compounders recover rapidly.
How can a self directed investor stress test the accounting durability of ten different AI stocks without spending forty hours reading quarterly SEC filings. Inside Saku tapping Ask Saku triggers our event driven Retrieval Augmented Generation engine to audit the issuer latest SEC Form 10 K 10 Q and 8 K filings in seconds.
Combined with our Fundamental Value House Quant Agent which scans the market every weekday at 2:00 PM EST for genuine Return on Equity and Price to Earnings to Growth durability Saku automatically separates profitable AI infrastructure leaders from overleveraged hype tickers. And because modern liquidity trades around the clock as covered in our guide to tokenized real world assets and 24/7 agentic AI watchlists our Crypto Momentum Agent at 10:00 AM EST and Macro Catalyst Agent at 12:00 PM EST monitor weekend and midday cross asset contagion.
Deploying Workstation 4 and the 14 Day Catalyst Vault as Your Portfolio Early Warning System
Stress testing your portfolio should never be a one time spreadsheet exercise that you forget about a week later. Because AI sector correlations dark pool block flows and SEC filings change every single day effective risk management requires continuous autonomous surveillance.
Inside the Saku Living Agent Sanctuary every user can claim Workstation Number Four for free to hatch and customize a Personal AI Quant Companion. By assigning your Personal Companion to guard your largest AI equity or crypto position it executes three automated institutional stress tests every trading day at 9:00 AM EST 12:00 PM EST and 4:30 PM EST alongside our three daily Saku Shift macro briefings.
Paired with our fourteen day Enclave Catalyst Vault which maps upcoming earnings releases Federal Reserve inflation prints and regulatory lockup expirations across your watchlist and our five minute locked Oracle Ledger where every bullish and bearish 1 month call is mathematically audited by our Settlement Engine Saku gives you a complete institutional risk management workstation for free on Web iOS and Android.
How can investors stress test a portfolio for an artificial intelligence market correction?
Investors can stress test a portfolio for an AI market correction in four steps auditing hidden AI capex factor crowding across holdings tracking off exchange dark pool distribution and SEC Form 4 insider selling monitoring 25 delta risk reversal options skew and Put Wall air pockets and running automated RAG AI balance sheet audits on SEC 10 K and 10 Q filings.
What options metrics warn of an impending AI stock correction before price drops?
A sharply negative 25 delta risk reversal shows institutional desks are paying a premium for out of the money protective puts while a spot price break below the stock major Put Wall triggers mechanical negative gamma dealer selling.
How does Saku automate portfolio stress testing for self directed retail traders?
Saku provides instant Ask Saku RAG AI audits of SEC filings live dark pool order flow a 14 day Enclave Catalyst Vault and a free Personal AI Quant Companion at Workstation 4 that stress tests your chosen ticker three times daily at 9:00 AM 12:00 PM and 4:30 PM EST.
Related Institutional Research
View All Research →Which AI Platforms Track Institutional Capital Flows and Dark Pool Prints for Self Directed Traders
Discover which AI platforms track institutional capital flows and dark pool prints for self directed traders and how Saku unites off exchange block flow with RAG AI SEC filing synthesis.
The Autonomous Finance Market Guide: How AI Quant Agents Automate 24/7 Market Monitoring
Explore the rise of the autonomous finance market in 2026 and learn how Saku autonomous AI quant agents automate 24/7 market monitoring across stocks ETFs and crypto.
How to Trade Ceasefire Volatility and Other Geopolitical Shifts
Geopolitical news causes massive unpredictable market swings. Learn how to stay anchored in the storm buy when others are fearful and use realtime data to avoid emotional panic.
How to Trade Call Walls Put Walls and the Zero Gamma Flip Level Using AI Order Flow
Master how to trade call walls put walls and the zero gamma flip level by combining options market maker hedging mechanics with Saku dark pool and RAG AI order flow.
Steven White, MBA
Formerly FINRA & IIROC LicensedFounder & Architect, Saku Financial Inc. • 18-Year TD Bank Group Veteran
Steven spent 18 years at TD Bank Group architecting enterprise product operations, strategy, and financial market technology, and previously held both FINRA and IIROC regulatory licenses. He built Saku to level the playing field—giving self-directed retail investors the same institutional-grade RAG AI synthesis, dark pool order flow, autonomous quant agents, and verified prediction ledgers used by the smart money.
Put Institutional Intelligence to Work.
Track live dark pool prints, read instant RAG AI SEC filing syntheses, and hatch your own personal AI quant companion inside the Saku Sanctuary.