

Time in the Market vs Timing the Market Long Term Conviction
Executive SynthesisStop trying to pick the absolute bottom. Discover why time in the market beats timing the market and how missing the best days destroys long term investing returns.
- Why does time in the market beat timing the market? Time in the market is superior because attempting to time the market often causes investors to miss the highest returning days which typically occur immediately after major sell offs destroying long term compounding.
- What is the cost of missing the best days in the stock market? Historical data proves that missing just the ten best days over a multi decade period can drastically reduce your annualized returns proving that holding through volatility is mathematically optimal.
- How does dollar cost averaging help long term investing? Dollar cost averaging eliminates the stress of market timing by investing a fixed amount of money at regular intervals ensuring you continuously acquire assets regardless of short term price fluctuations.
The Seduction of the Perfect Entry Point
Every retail investor eventually falls into the exact same psychological trap they attempt to outsmart global liquidity by predicting the exact bottom of a severe sell off. This desire to execute perfect market timing is driven by a natural human aversion to temporary portfolio drawdowns. We want the maximum mathematical reward with absolutely zero psychological discomfort.
However financial veterans have explicitly stated for decades that market timing is purely speculating and it rarely ever pays off. The fundamental flaw with this approach is that financial markets do not operate on clean predictable schedules. When global equities experience severe volatility the vast majority of retail traders retreat to cash assuming they can simply buy back in when the dust settles.
The problem is that the dust never settles cleanly. The transition from a brutal macroeconomic contraction to a massive bullish rally happens violently and without warning. If you are sitting on the sidelines waiting for a mainstream media anchor to give you the all clear signal you will inevitably buy back into the market at a massive premium completely destroying your long term investing returns.
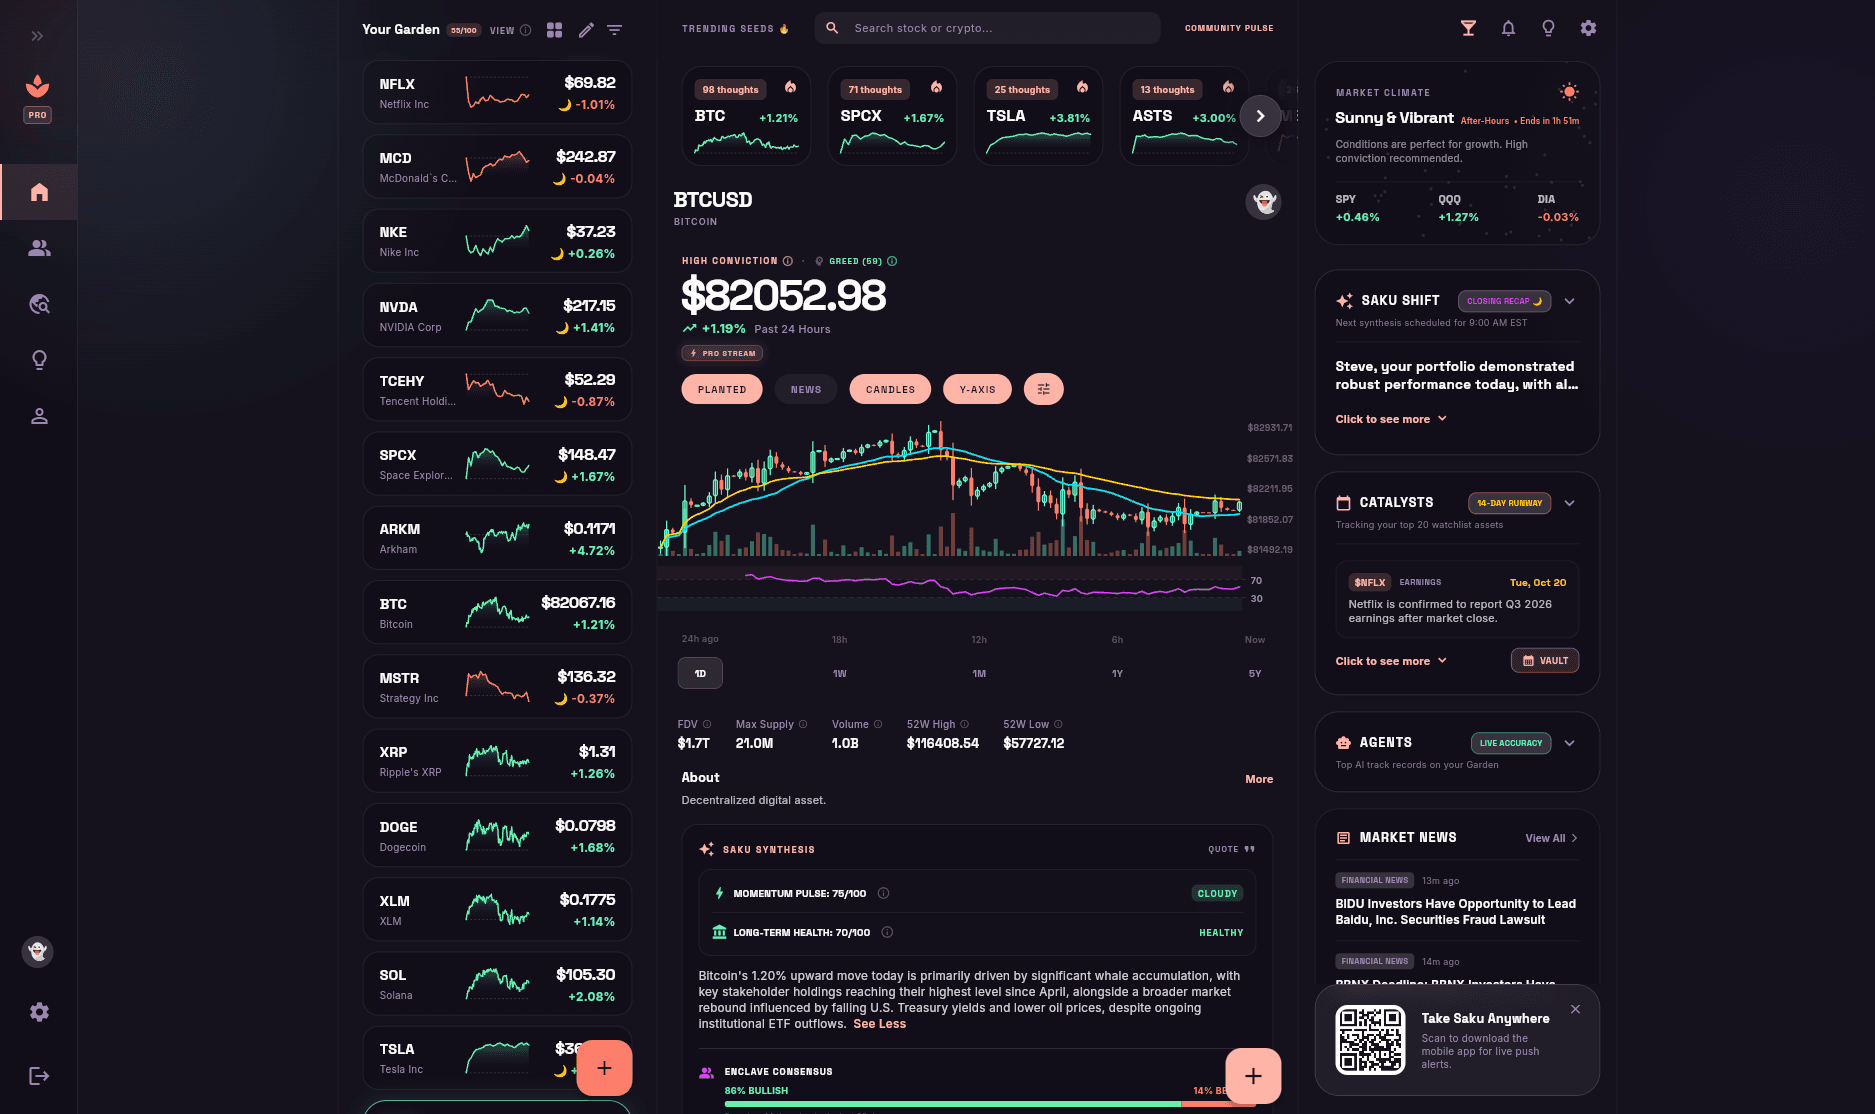
See Live Dark Pool Flow & AI SEC Synthesis in Action
Don't just read about institutional order flow—track it live on your favorite stock or crypto ticker right now.
The Mathematical Cost of Missing the Best Days
The debate between time in the market vs timing the market is not a matter of philosophical opinion it is a matter of cold audited mathematics. The stock market does not deliver its gains in a smooth linear fashion. The vast majority of wealth is generated during extremely condensed explosive windows of buying pressure.
Quantitative research highlights exactly how much it costs to miss the best days in the market. Over a recent thirty four year period an initial investment in the S and P five hundred would have generated an average annual return of over ten percent if left completely alone. However if a trader attempted to time the market and accidentally missed just the ten best days out of thousands of trading sessions their average annual return would instantly plummet to eight percent. Missing the thirty best days would drop their return to a dismal five percent.
Furthermore a commonly cited rule of thumb suggests that ninety percent of the absolute return in the market is typically generated on just ten percent of the trading days. Because the best days almost always occur immediately following the worst days investors who panic sell during a pullback mathematically guarantee their own failure. They absorb all of the downside risk and capture absolutely none of the explosive recovery.
| Market Intelligence Layer | Legacy Retail Apps | Saku AI Terminal (Free) |
|---|---|---|
| Support & Resistance Zones | Subjective retail trendlines | Mechanical Call/Put Walls, SMA/EMA & 1–100 Momentum Pulse |
| SEC Filings & Breaking News | Delayed headlines & raw 80-page PDFs | Instant event-driven RAG AI synthesis of Form 4, 8-K & 10-Q |
| 24/7 Market Surveillance | Manual price alerts only | 3 House Quants + Personal AI Companion at Workstation #4 |
| Prediction Accountability | Unverified social posts (deleted losses) | 5-Minute Write-Locked Oracle Ledger & Precision Grading |
The Fallacy of Market Forecasting
To successfully time the market you have to be right twice. You have to perfectly predict when an asset has reached its absolute peak to sell and you have to perfectly predict when the asset has reached absolute bottom to buy back in. Executing this flawlessly over a multi decade time horizon is statistically impossible.
Even institutional experts fail at short term forecasting. Analysts frequently project modest gains during years when the market roars higher and project strong growth directly before massive economic recessions. If teams of quantitative analysts backed by supercomputers cannot consistently predict short term price action a retail trader relying on basic technical indicators has zero chance.
This is why time in the market is the ultimate equalizer. By remaining invested you completely remove the requirement to be a perfect forecaster. The broader macroeconomic trend of global equities is undeniably upward over an extended time horizon. You simply have to deploy your capital and let institutional liquidity and corporate earnings compound your wealth over time.
Track live dark pool flow & hatch your Personal AI Quant at Desk #4.
Dollar Cost Averaging vs Lump Sum Panic
For investors terrified of deploying capital at a market top the optimal solution is not sitting in cash. The solution is implementing a strict dollar cost averaging framework. This strategy involves investing a fixed amount of capital at regular intervals regardless of what the underlying asset price is doing.
By purchasing shares every single week or month you naturally buy more shares when the price is cheap and fewer shares when the price is expensive. Dollar cost averaging completely eliminates the emotional paralysis of trying to pick the perfect entry point. It automates your discipline and ensures continuous participation in the global capital markets.
Research shows that while lump sum investing often wins in historical backtesting because the market trends upward over time dollar cost averaging provides the ultimate psychological safety net. It allows you to build massive long term positions without constantly stressing over intraday volatility or impending central bank rate decisions.
How Saku Reinforces Long Term Conviction
Building the patience required to survive severe market volatility is incredibly difficult when using legacy brokerage applications. Traditional platforms use flashing red indicators and chaotic news feeds to induce anxiety and trigger emotional selling. Saku completely reverses this toxic psychological environment.
We engineered Saku to serve as a digital sanctuary for long term investors. By utilizing a zero ad terminal aesthetic we eliminate the commercial noise that causes cognitive fatigue. More importantly our dynamic Zen Garden transforms arbitrary price tracking into a living visual ecosystem.
When you establish an investment thesis on Saku you plant a digital seed. As time passes and the asset matures your seed physically grows into a tree. This purposeful gamification subconsciously trains your brain to value patience over frantic trading. It provides the visual reinforcement required to hold your conviction when the algorithms try to shake you out of your position.
Building Generational Wealth Through Patience
The greatest transfer of wealth in financial markets flows from the impatient trader to the patient investor. Every time you attempt to time a market top or short a temporary pullback you are abandoning a proven mathematical reality for a high risk speculative gamble.
Stop letting fear and greed dictate your financial trajectory. Embrace the indisputable power of time in the market utilize the Saku ecosystem to automate your macroeconomic intelligence and build a portfolio designed to withstand any phase of the business cycle.
Why does time in the market beat timing the market?
Time in the market is superior because attempting to time the market often causes investors to miss the highest returning days which typically occur immediately after major sell offs destroying long term compounding.
What is the cost of missing the best days in the stock market?
Historical data proves that missing just the ten best days over a multi decade period can drastically reduce your annualized returns proving that holding through volatility is mathematically optimal.
How does dollar cost averaging help long term investing?
Dollar cost averaging eliminates the stress of market timing by investing a fixed amount of money at regular intervals ensuring you continuously acquire assets regardless of short term price fluctuations.
Related Institutional Research
View All Research →Crowdsourced Financial Intelligence Building a Decentralized Community
Discover how crowdsourced financial intelligence and decentralized investment research empower retail traders to build their own tools and outperform legacy institutions.
Autonomous AI Agents in Financial Markets Your Personal Quant Desk
Explore the future of retail trading where autonomous artificial intelligence agents embedded in Saku Pro monitor global markets and execute complex research tasks while you sleep.
Real Time AI Market Surveillance and Asset Synthesis Explained
Discover how Saku AI monitors real time market liquidity tracks price anomalies and communicates asset movements instantly using advanced synthesis engines.
The Death of the 1980s Financial Terminal The Rise of Agentic AI Workstations
Discover why legacy 1980s financial terminals and ad bloated retail brokerages are obsolete and explore how Saku agentic AI workstations synthesize market alpha.
What is a Put Wall in Options Trading Mechanical Support and Negative Gamma Explained
Learn what a put wall is in options trading why major put gamma strikes act as mechanical support floors and how Saku tracks put walls and dark pool absorption.
Retrieval Augmented Generation in Finance How RAG Explains Market Moves
Discover how Retrieval Augmented Generation bridges live market feeds and artificial intelligence to give retail investors instant explanations for why markets are moving.
Steven White, MBA
Formerly FINRA & IIROC LicensedFounder & Architect, Saku Financial Inc. • 18-Year TD Bank Group Veteran
Steven spent 18 years at TD Bank Group architecting enterprise product operations, strategy, and financial market technology, and previously held both FINRA and IIROC regulatory licenses. He built Saku to level the playing field—giving self-directed retail investors the same institutional-grade RAG AI synthesis, dark pool order flow, autonomous quant agents, and verified prediction ledgers used by the smart money.
Put Institutional Intelligence to Work.
Track live dark pool prints, read instant RAG AI SEC filing syntheses, and hatch your own personal AI quant companion inside the Saku Sanctuary.