

Buy and Hold vs Timing the Market: How AI Quant Agents Combine Long Term Conviction with Tactical Alpha
Executive SynthesisResolve the buy and hold vs timing the market debate by learning how Saku autonomous AI quant agents combine long term compounding with tactical dark pool and options gamma entries.
Why the Buy and Hold vs Timing the Market Debate Is a False Binary
For over fifty years retail financial literature has presented self directed investors with a rigid binary choice buy and hold passive index funds blindly through every macroeconomic cycle or attempt to time the market by jumping completely into cash and guessing exact market tops and bottoms. Traditional wealth managers cite historical data showing that missing just the ten best single day rallies of a decade cuts a portfolio compounded return in half.
While that mathematical truth proves why Emotional All or Nothing Market Timing fails it ignores how institutional asset managers sovereign wealth funds and multi strategy quantitative pods actually manage capital in late 2026. Elite institutions never liquidate their entire portfolio into cash to guess a macro bottom nor do they buy wildly overextended stocks at overhead options resistance ceilings. Instead they combine core long term compounding with tactical quantitative rebalancing.
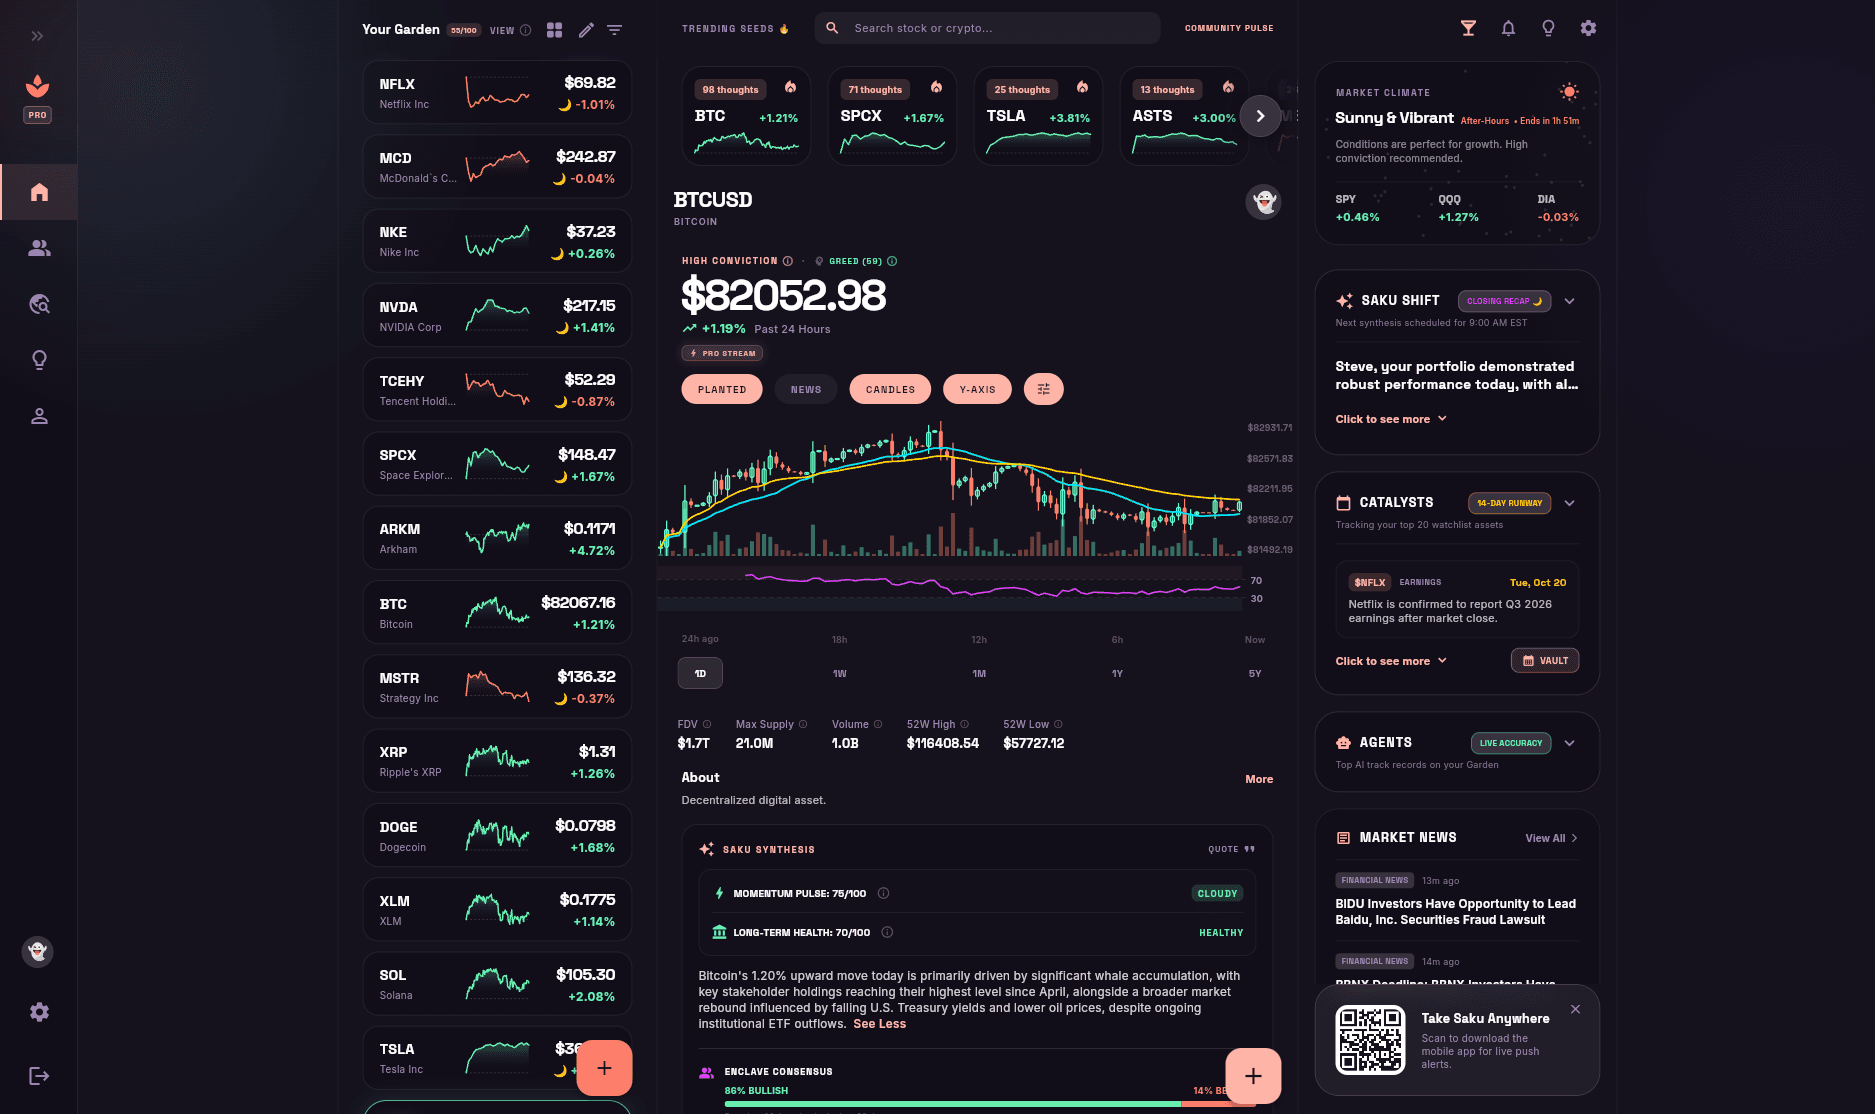
Having spent eighteen years inside enterprise banking at TD Bank Group architecting financial market technology and holding both FINRA and IIROC regulatory licenses I watched institutional portfolio desks execute this exact hybrid discipline every single day. We built Saku Financial Inc. to give self directed investors a 100 percent free ad free AI terminal across Web iOS and Android that unites long term fundamental conviction with tactical institutional entry timing.
See Live Dark Pool Flow & AI SEC Synthesis in Action
Don't just read about institutional order flow—track it live on your favorite stock or crypto ticker right now.
Why Emotional Market Timing Fails While Quantitative Execution Succeeds
To understand why retail investors lose money when timing the market vs time in the market we must examine human behavioral psychology during volatility cascades. Over seventy six percent of the stock market largest single day rebound surges occur directly inside bear market drawdowns or within two weeks of a panic capitulation low. Retail traders who sell out of fear after a ten percent correction almost always miss the violent institutional short squeeze that follows.
Why does emotional timing fail so consistently. Because human traders rely on lagging financial news headlines social media sentiment and gut instinct rather than real time market microstructure. When you try to time entries and exits using raw candlestick charts alone you end up buying into retail euphoria right below an institutional Call Wall ceiling and panic selling right at a mechanical Put Wall floor.
As we demonstrated in our foundational studies on time in the market vs timing the market for long term conviction and quantitative rebalancing and AI alpha the solution is not to abandon tactical execution. The solution is to replace emotional guesswork with deterministic quantitative signals.
How Saku Dual Scores Unite Buy and Hold Health with Tactical Momentum
How do you mathematically separate a stock long term buy and hold quality from its short term tactical entry timing. Inside the Saku terminal every equity exchange traded fund and digital asset is evaluated continuously across two independent quantitative state vectors the Long Term Health Score and the Momentum Pulse Score.
Your Long Term Health Score graded from zero to one hundred measures the fundamental buy and hold durability of the business by auditing SEC Form 10 K and 10 Q balance sheet solvency free cash flow compounding Return on Equity and valuation compression via our Retrieval Augmented Generation engine. Meanwhile your Momentum Pulse Score graded from zero to one hundred measures short term tactical velocity across five day price momentum fourteen day Relative Strength Index loops fifty day Simple and Exponential Moving Average spreads and relative volume anomalies.
Whether you are building a core position inside our programmatic NVDA AI price target and dark pool quant analysis or tracking broad index liquidity inside our SPY AI price target and support levels dossier pairing a high Long Term Health Score with a tactical pullback to structural support gives you the best of both worlds.
Track live dark pool flow & hatch your Personal AI Quant at Desk #4.
Using Dark Pools Call Walls and SEC Form 4 Clusters to Time Tactical Additions
Once you have selected high conviction assets for your long term portfolio how do you time your monthly capital additions or dividend reinvestments like an institutional quant desk. Instead of buying blindly at 9:30 AM on a random morning when retail order flow is widest you audit three institutional liquidity boundaries inside Saku.
First you inspect the options gamma channel. As we detailed in our tactical playbook on how to trade call walls put walls and the zero gamma flip level adding to your long term winners when spot price pulls back to a major mechanical Put Wall support floor aligns your capital directly with options market maker buying hedges rather than chasing price into an overhead Call Wall ceiling.
Second you verify off exchange institutional accumulation and executive conviction. By cross referencing live dark pool block prints with our SEC Form 4 automation guide to executive insider buying clusters you can deploy new capital at the exact moment corporate executives and institutional dark pools are absorbing shares on the open market.
Automating Your Core and Tactical Strategy with Personal AI Quant Agents
The biggest reason self directed investors default to passive set and forget indexing is that nobody has time to monitor dark pool prints SEC filings and options support walls during a busy workday. Inside the Saku Living Agent Sanctuary our autonomous quant architecture automates that entire workflow for you.
Every day our three autonomous House Quant Agents model disciplined 1 month conviction calls on a fixed schedule Crypto Momentum at 10:00 AM EST seven days a week Macro and Catalysts at 12:00 PM EST weekdays and Fundamental Value at 2:00 PM EST weekdays. Even better as we explored in our breakdown of personal AI stock agents use cases every Saku user can claim Workstation Number Four for free to hatch and customize a Personal AI Quant Companion.
Your Personal Companion guards your core buy and hold stock twenty four hours a day delivering automated shift dossiers at 9:00 AM EST 12:00 PM EST and 4:30 PM EST alongside our three daily Saku Shift briefings. When your long term compounder pulls back to its structural support floor or experiences a burst of institutional dark pool accumulation your agent alerts you immediately.
Visualizing Long Term Conviction in Your 3D Zen Garden and Oracle Ledger
Why do legacy brokerage apps trick long term buy and hold investors into overtrading. Because legacy apps use casino style flashing red and green ticks and noisy social feeds that trigger dopamine spikes and panic selling.
Saku was architected around Japanese Zen craft aesthetics to cultivate calm disciplined conviction. As you allocate seeds to your 1 month stock ETF or crypto theses inside Saku your positions physically grow inside your living 3D Zen Garden blossoming into full Sakura trees as your thesis plays out. Every prediction is write locked after five minutes on our public Oracle Ledger and mathematically audited at expiration by our quantitative Settlement Engine.
Stop choosing between blind buy and hold passivity and emotional market timing. Launch the 100 percent free ad free Saku terminal on Web iOS or Android today to combine long term compounding with institutional AI precision.
Which is better buy and hold vs timing the market?
Pure emotional market timing moving 100 percent in and out of cash consistently underperforms buy and hold investing because 76 percent of the market best rebound days cluster inside drawdowns. However combining core buy and hold compounding with quantitative tactical entries at options Put Wall support floors and dark pool accumulation zones generates superior risk adjusted returns.
How do Saku AI agents help long term buy and hold investors?
Saku provides a Long Term Health Score (0 to 100) based on RAG AI audits of SEC 10 K and 10 Q filings alongside a free Personal AI Quant Companion at Workstation 4 that guards your core holding 24/7 and delivers shift briefings at 9:00 AM 12:00 PM and 4:30 PM EST.
What indicators should investors check before adding to a long term stock position?
Before adding capital to a long term position self directed investors can check Saku daily support floor (Put Wall) and resistance ceiling (Call Wall) levels verify whether off exchange dark pool flow shows institutional accumulation and audit recent SEC Form 4 filings for Code P executive insider buying.
Related Institutional Research
View All Research →Best AI Agents to Monitor the Stock Market 24/7: How Autonomous Quant Companions Guard Your Watchlist
Looking for AI agents to monitor the stock market and crypto 24/7? Discover how Saku autonomous House Quant Agents and your free Personal AI Companion at Workstation 4 audit dark pools SEC filings and support walls nonstop.
25d Risk Reversal ETH and Deribit 25 Delta Risk Reversal Definition: Crypto and Equity Options Skew Guide
Master the 25d risk reversal ETH metric and Deribit 25 delta risk reversal definition to decode institutional crypto options skew crash hedging and cross asset equity flows on Saku.
From a Big 5 Bank to Retail FinTech: Why I Built Saku
After 18 years of enterprise banking experience I saw the massive data disparity between Wall Street and Main Street. Here is the exact story of why I decided to level the playing field.
SEC Form 4 Automation Guide: How AI Tracks Executive Insider Buying Clusters in Real Time
Learn how SEC Form 4 automation works on Saku and how our event driven RAG AI separates high conviction Code P open market executive insider buying clusters from routine 10b5 1 compensation noise.
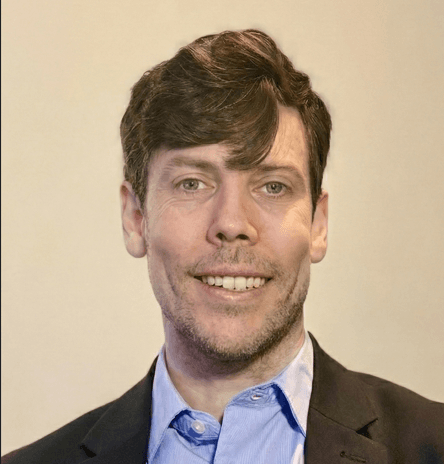
Steven White, MBA
Formerly FINRA & IIROC LicensedFounder & Architect, Saku Financial Inc. • 18-Year TD Bank Group Veteran
Steven spent 18 years at TD Bank Group architecting enterprise product operations, strategy, and financial market technology, and previously held both FINRA and IIROC regulatory licenses. He built Saku to level the playing field—giving self-directed retail investors the same institutional-grade RAG AI synthesis, dark pool order flow, autonomous quant agents, and verified prediction ledgers used by the smart money.
Put Institutional Intelligence to Work.
Track live dark pool prints, read instant RAG AI SEC filing syntheses, and hatch your own personal AI quant companion inside the Saku Sanctuary.